Apply Pressure
To Your Credit
Stop Getting Denied. Start Getting Approved.
We help clients remove inaccurate negative items, rebuild their credit
profile, and position themselves for real financial opportunities.
Your credit affects everything.
Cars. Homes. Funding. Lifestyle.
At Pressure Financial Services, we don’t just focus on
raising scores we focus on helping you build a stronger
financial profile that leads to real approvals.
Whether you’re trying to buy a home, get approved for a vehicle,
secure funding, or simply regain financial confidence, we help guide
you step-by-step through the process.
Apply Pressure
To Your Credit
Stop Getting Denied. Start Getting Approved.
We help clients remove inaccurate negative items, rebuild their credit
profile, and position themselves for real financial opportunities.
Your credit affects everything.
Cars. Homes. Funding. Lifestyle.
At Pressure Financial Services, we don’t just focus on
raising scores we focus on helping you build a stronger
financial profile that leads to real approvals.
Whether you’re trying to buy a home, get approved for a vehicle,
secure funding, or simply regain financial confidence, we help guide
you step-by-step through the process.
HOW OUR PROCESS WORKS
Our Client Journey Process
Simple. Strategic. Results-Driven.
Step 1 - Awareness
You Realize Something Needs To Change
You’re tired of getting denied.
You’re tired of feeling stuck financially.
And now you’re ready to take control of your credit and future.
Step 2 - Consultation & Qualification
We Learn Your Goals
We start with a consultation to understand:
Your current situation
Your financial goals
What’s hurting your credit profile
We also set realistic expectations
and explain the process clearly.
Step 3 - Enrollment & Payment
Officially Get Started!
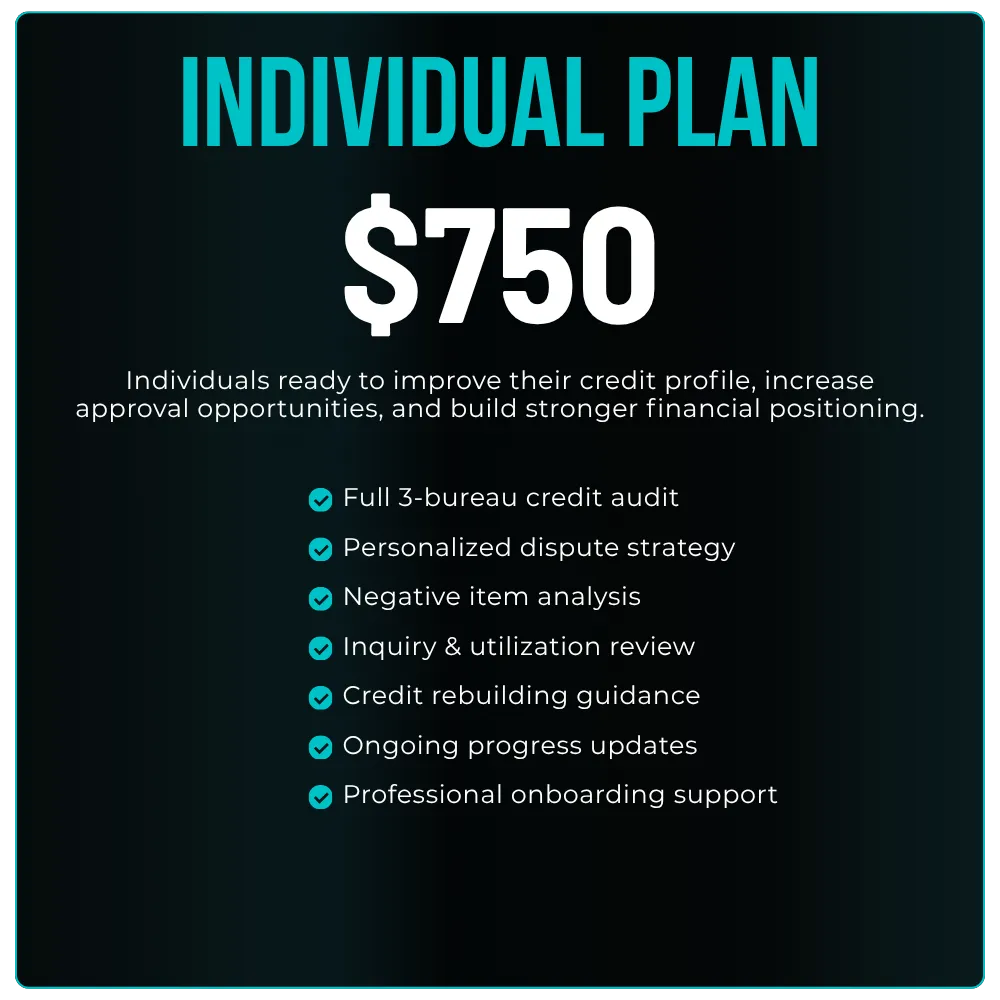
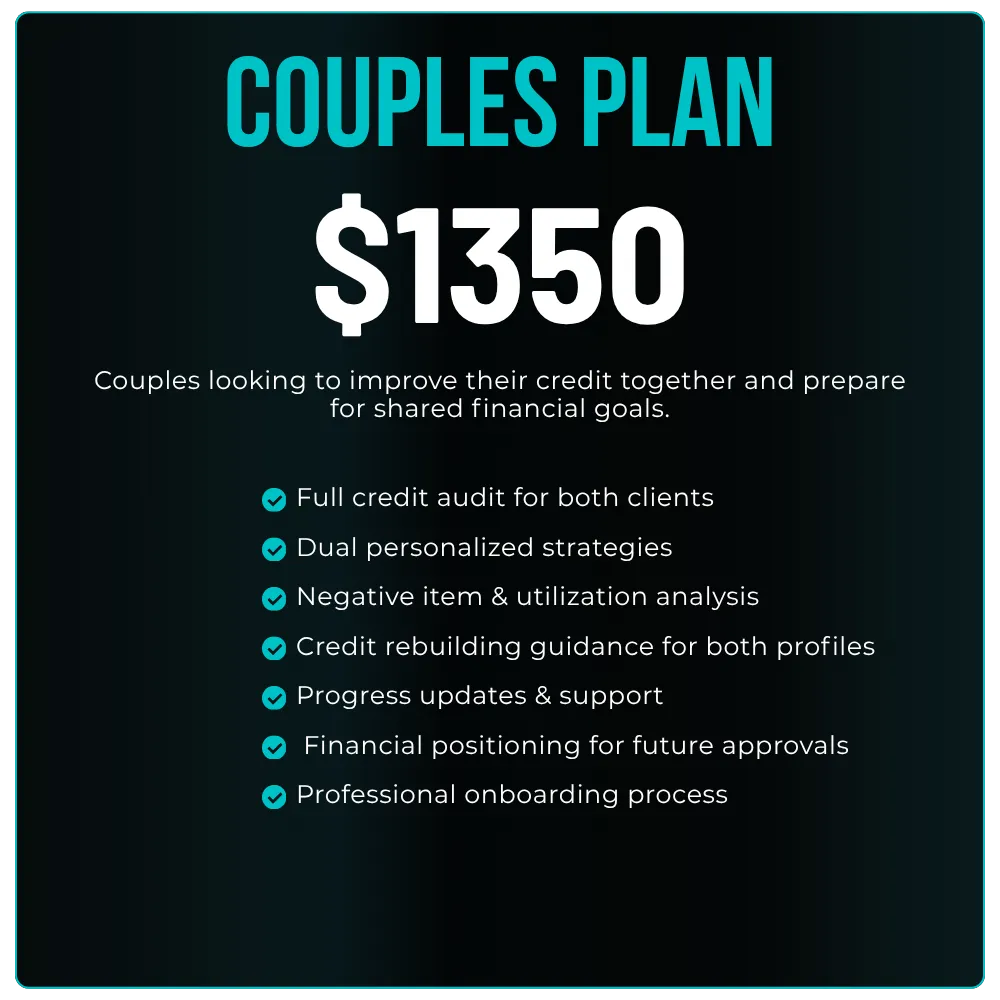
Choose the plan that fits your needs:
And the worst part?
Most people don’t even know where to start.
That’s where we come in.
HOW OUR PROCESS WORKS
Our Client Journey Process
Simple. Strategic. Results-Driven.
Step 1 - Awareness
You Realize Something Needs To Change
You’re tired of getting denied.
You’re tired of feeling stuck financially.
And now you’re ready to take
control of your credit and future.
Step 2 - Consultation & Qualification
We Learn Your Goals
We start with a consultation to understand:
Your current situation
Your financial goals
What’s hurting your credit profile
We also set realistic expectations
and explain the process clearly.
Step 3 - Enrollment & Payment
Officially Get Started!
Choose the plan that fits your needs:
Meet Chare Smith
I’m passionate about helping individuals and families take control of their financial future by restoring and strengthening their credit. With a strong background in credit repair and financial education, I specialize in turning “denied” into “approved” and helping my clients unlock opportunities they once thought were out of reach.
My goal is to provide more than just credit improvement, I focus on helping clients build confidence, create better financial habits, and position themselves for long-term success.
I believe credit is more than just a score. It’s a tool that can help open doors to homeownership, vehicle approvals, business funding, and financial freedom when managed the right way.
Through strategic guidance, personalized solutions, and ongoing support, I’m committed to helping my clients move differently financially and create a stronger future for themselves and their families.
Meet Chare Smith
I’m passionate about helping individuals and families take control of their financial future by restoring and strengthening their credit. With a strong background in credit repair and financial education, I specialize in turning “denied” into “approved” and helping my clients unlock opportunities they once thought were out of reach.
My goal is to provide more than just credit improvement, I focus on helping clients build confidence, create better financial habits, and position themselves for long-term success.
I believe credit is more than just a score. It’s a tool that can help open doors to homeownership, vehicle approvals, business funding, and financial freedom when managed the right way.
Through strategic guidance, personalized solutions, and ongoing support, I’m committed to helping my clients move differently financially and create a stronger future for themselves and their families.
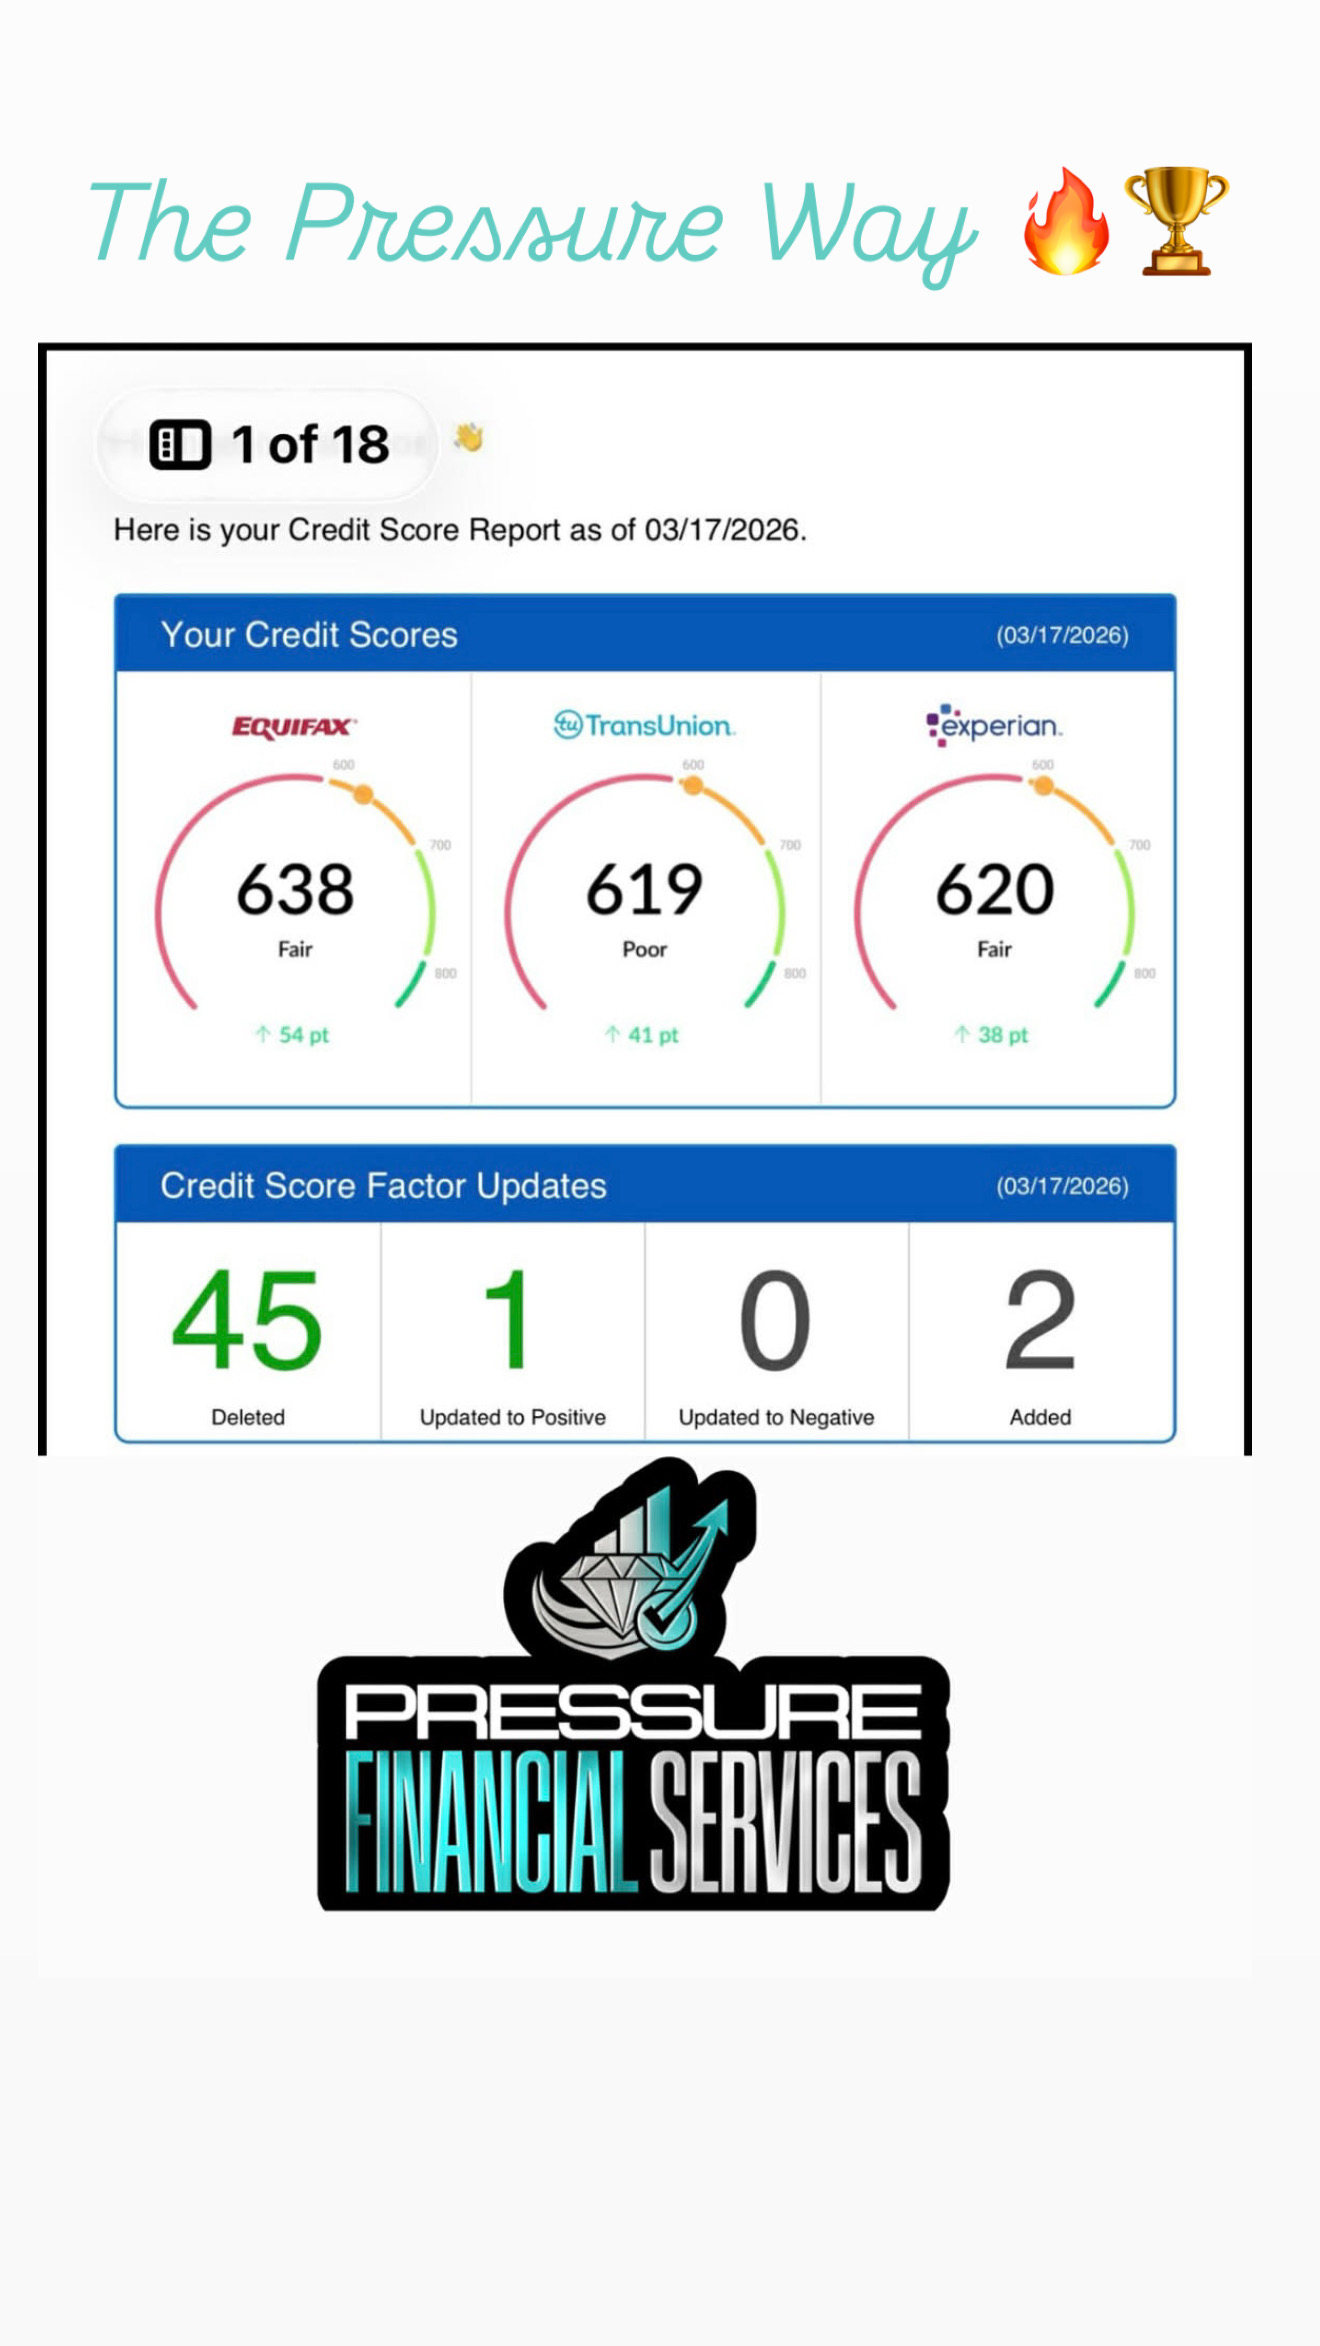
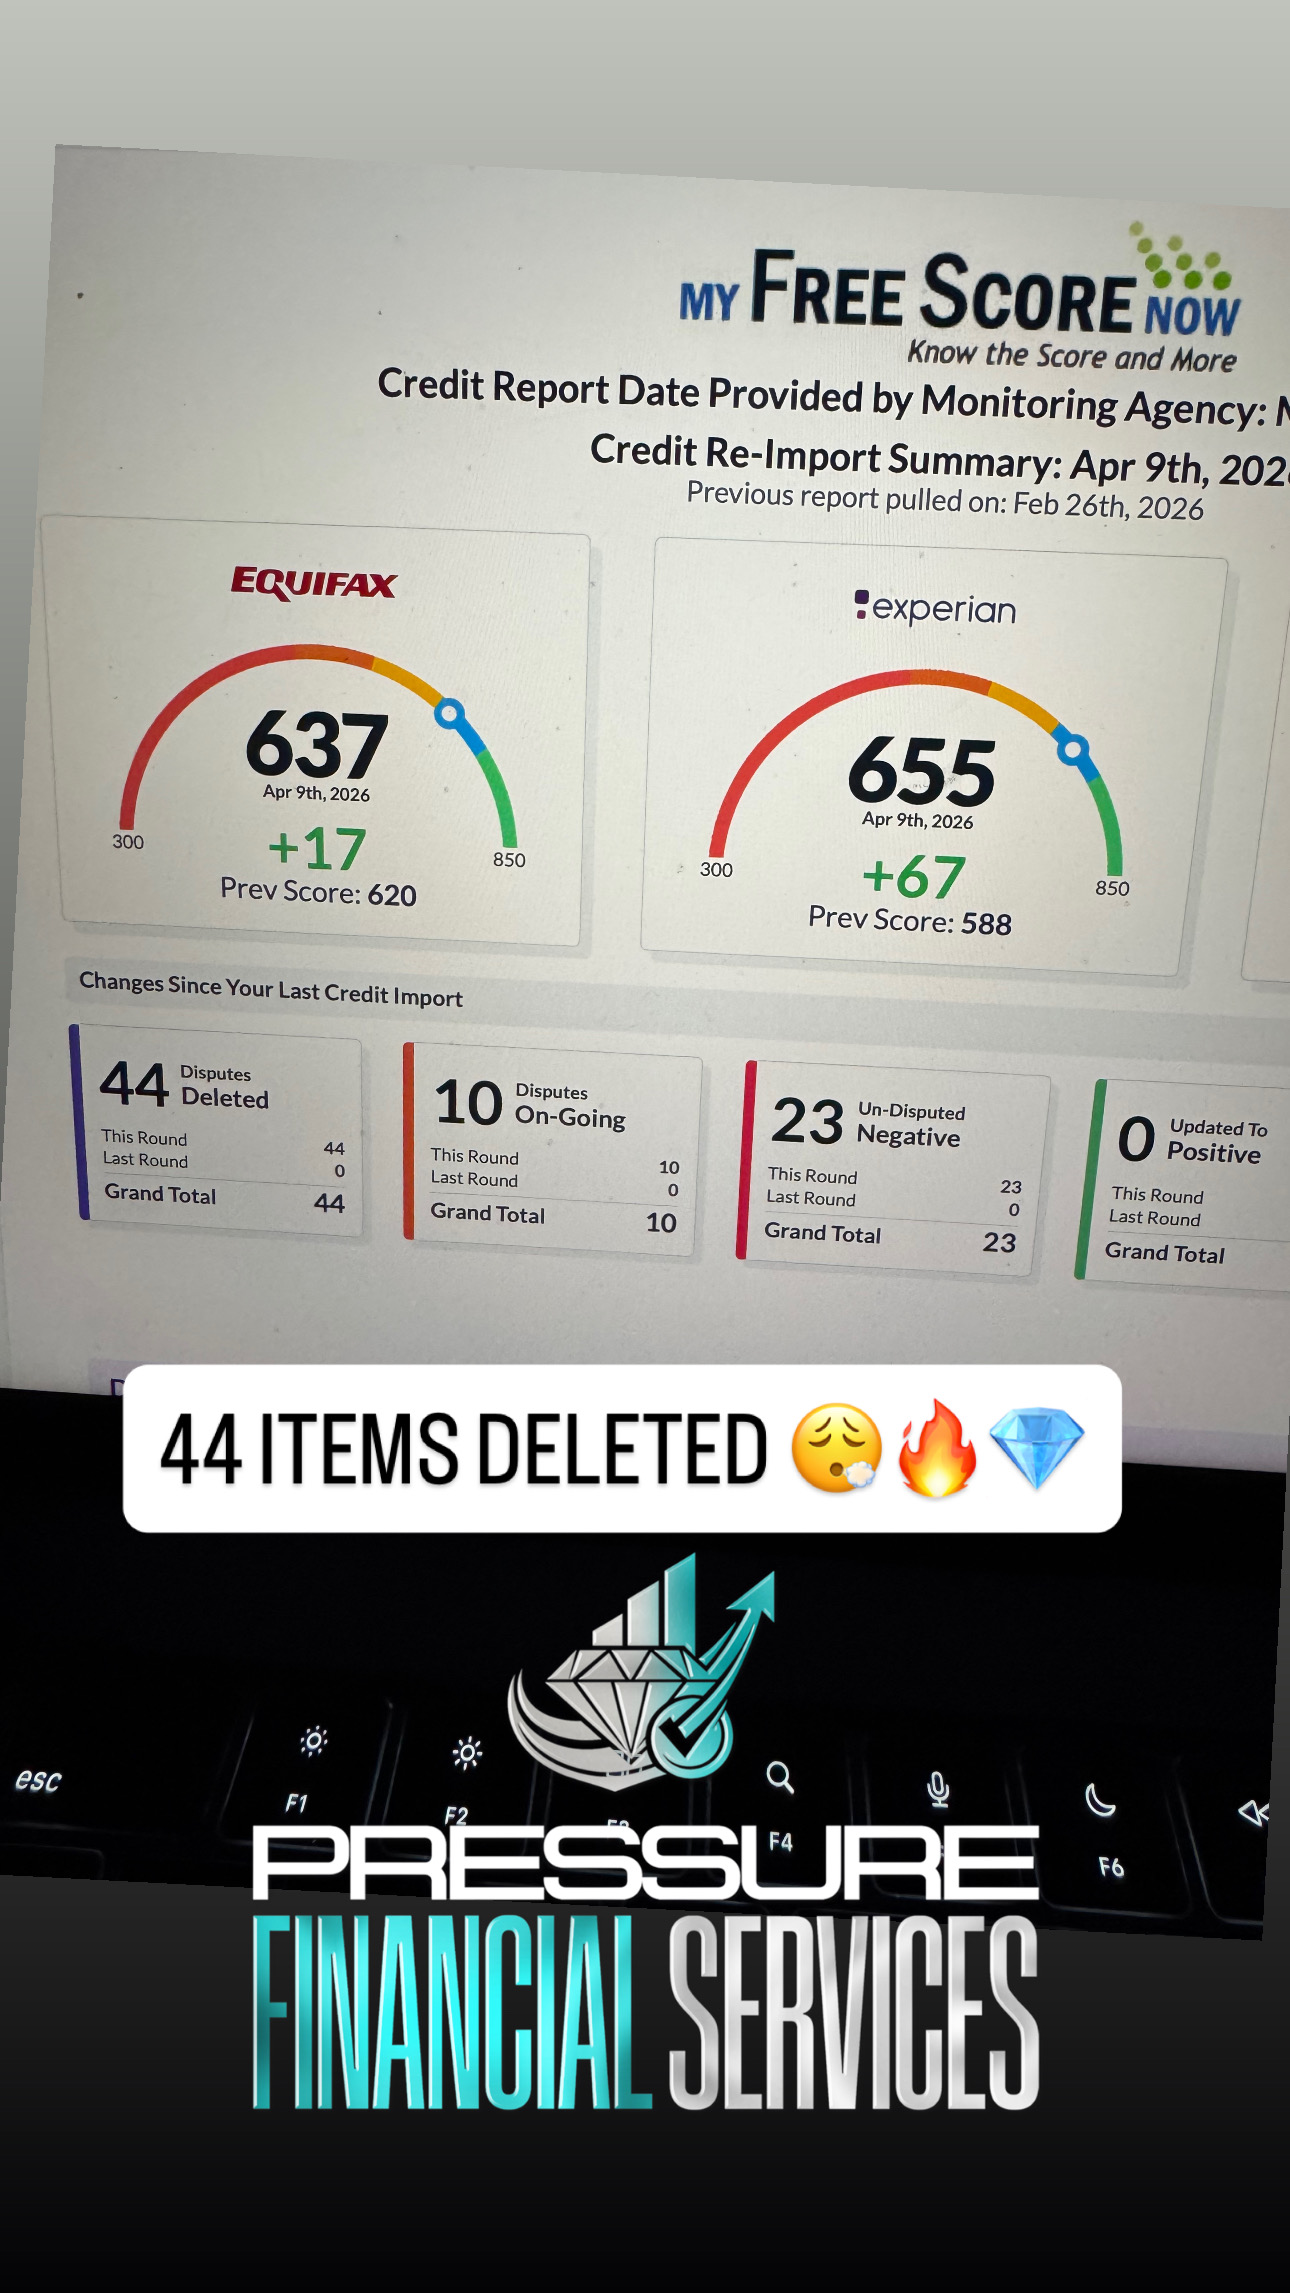
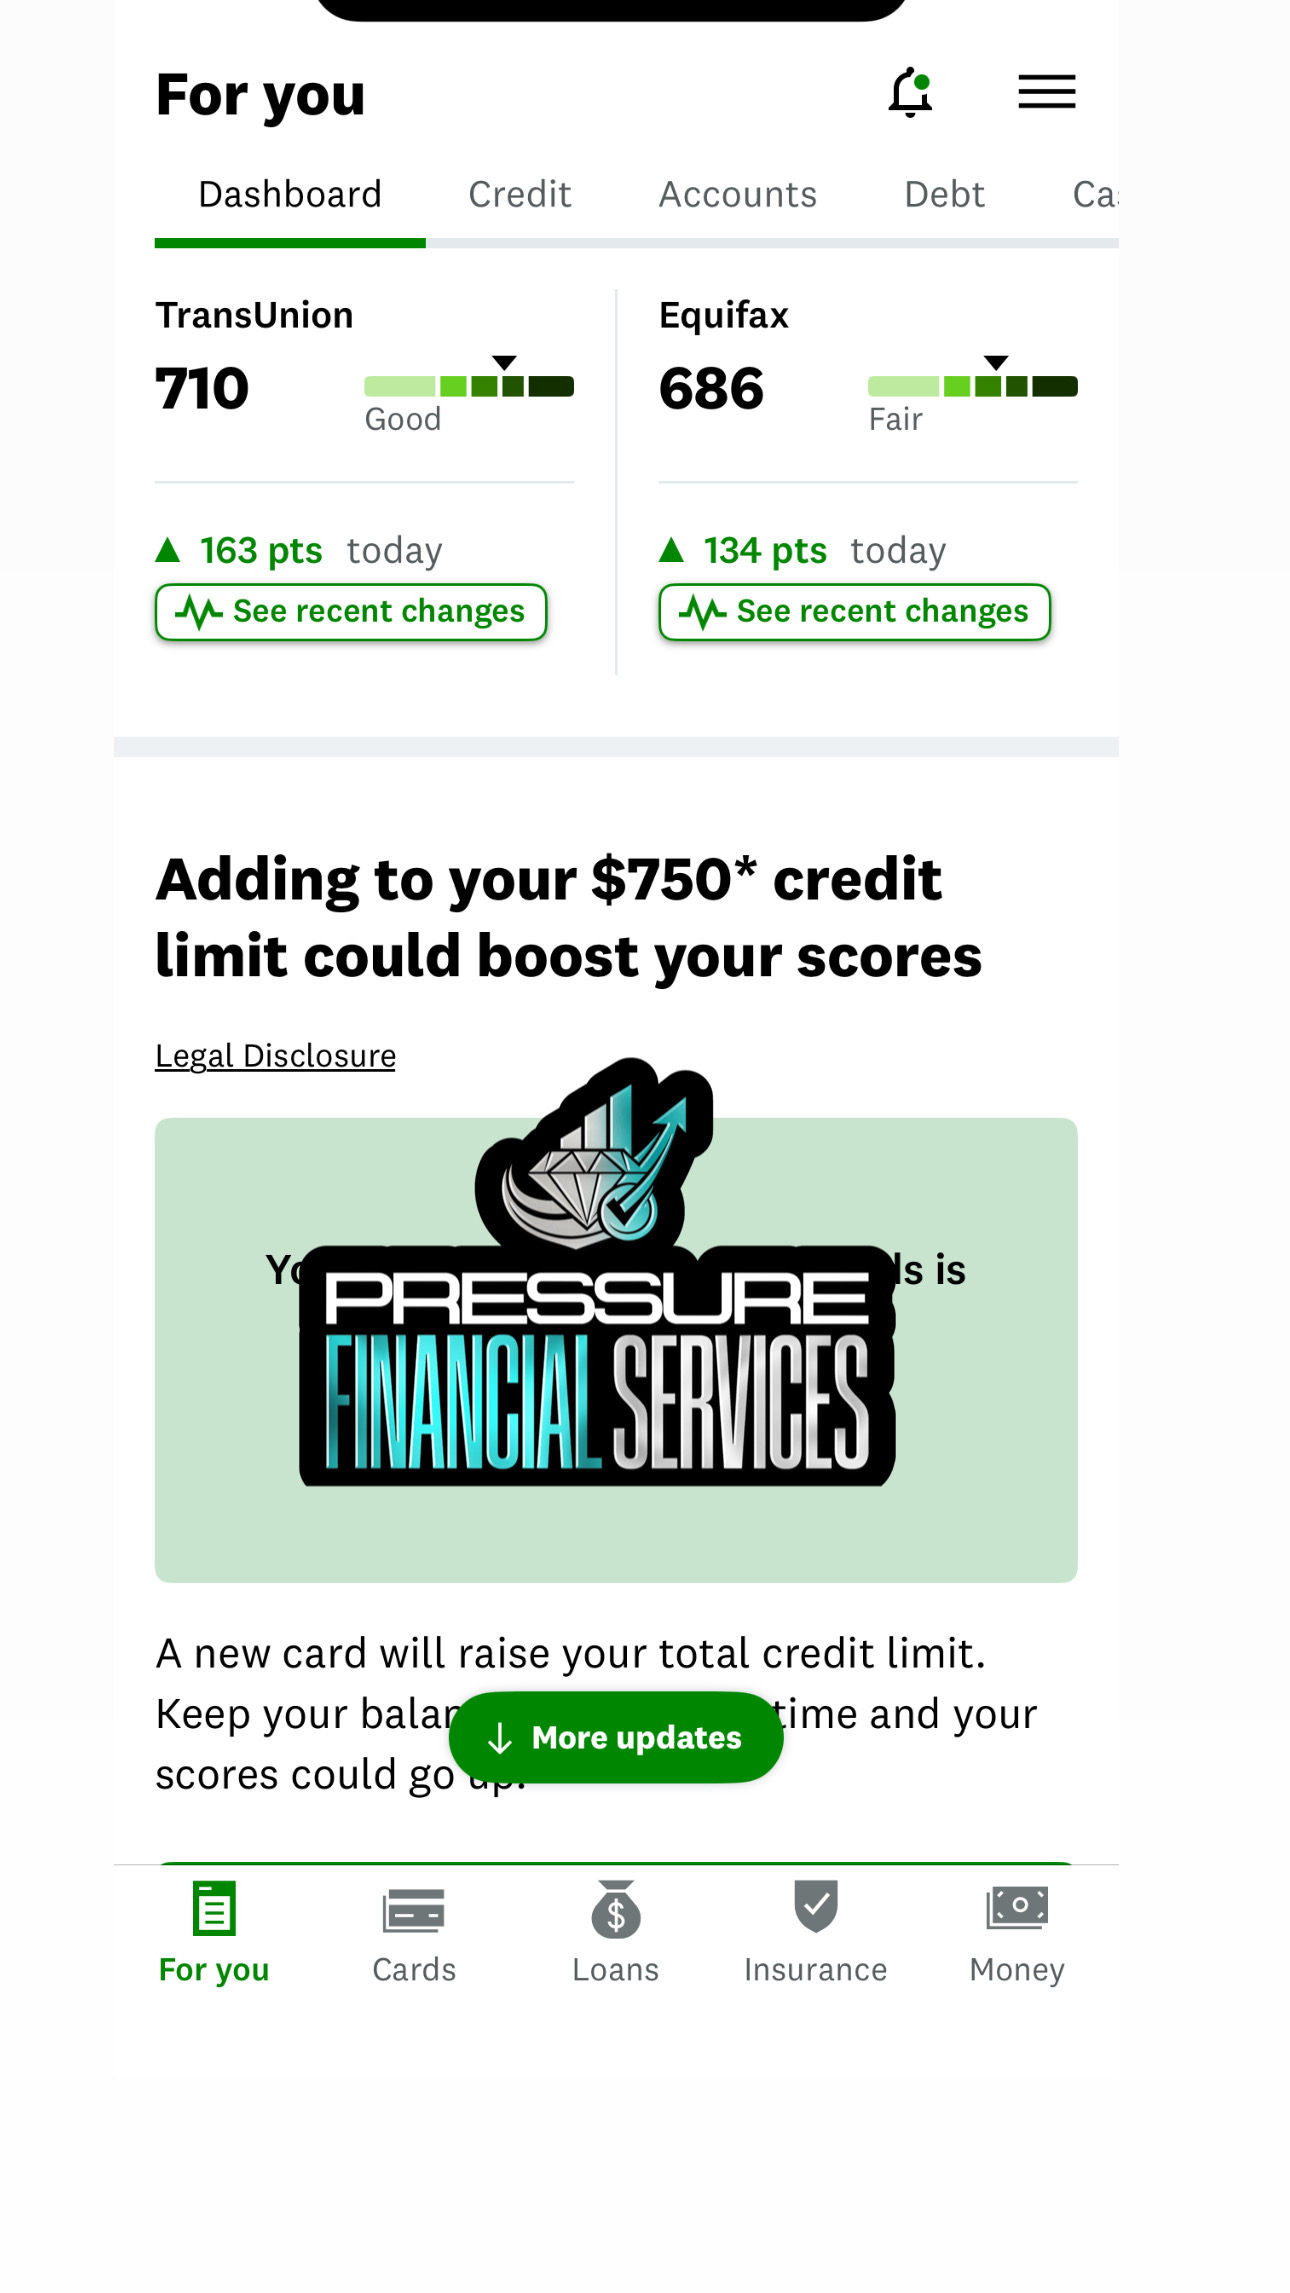
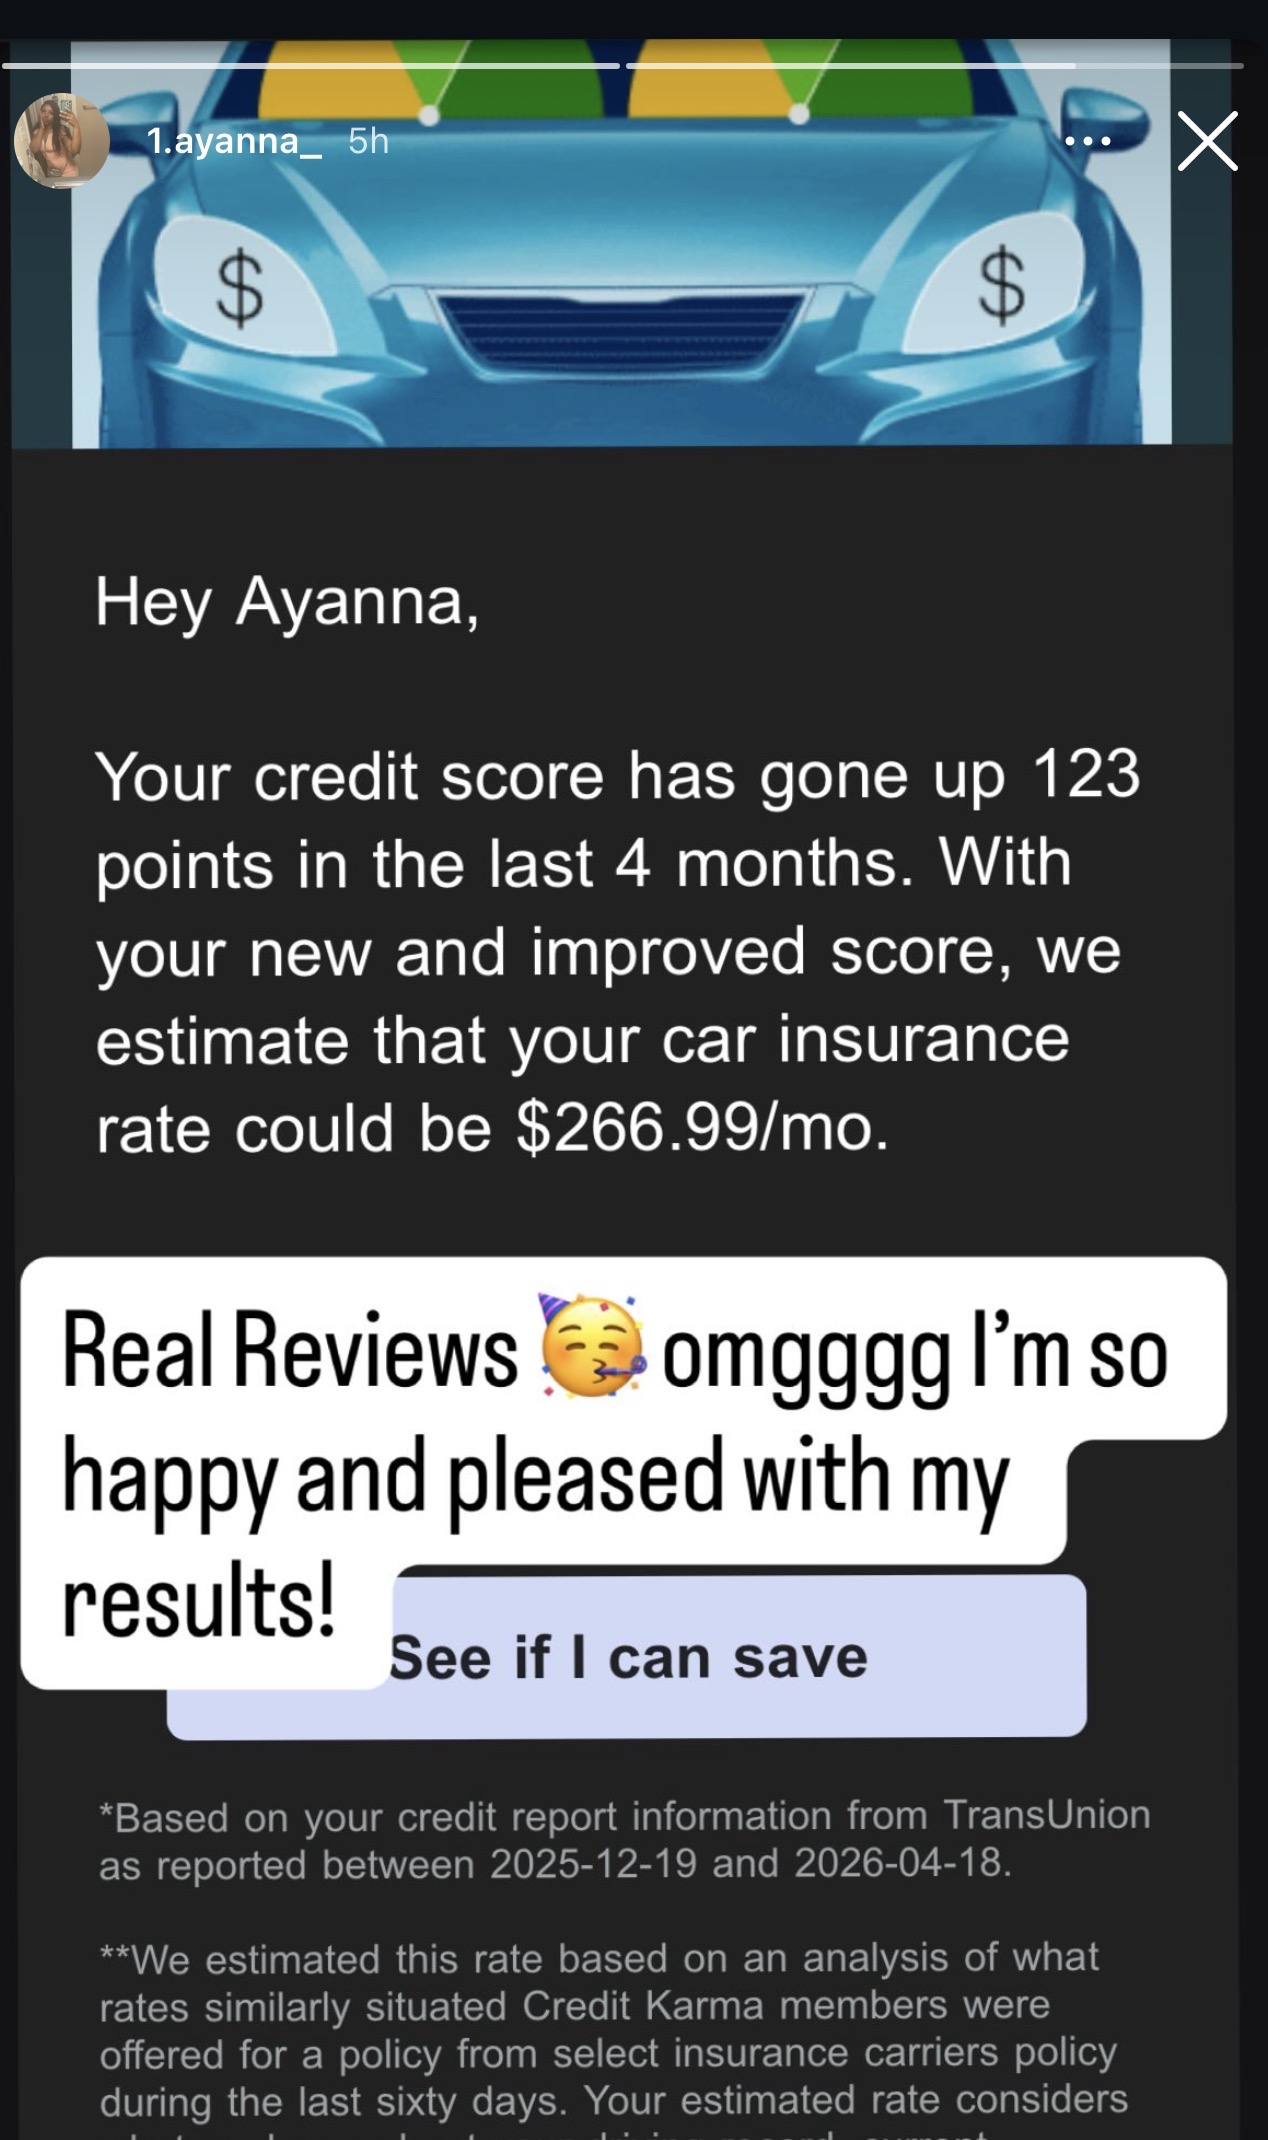
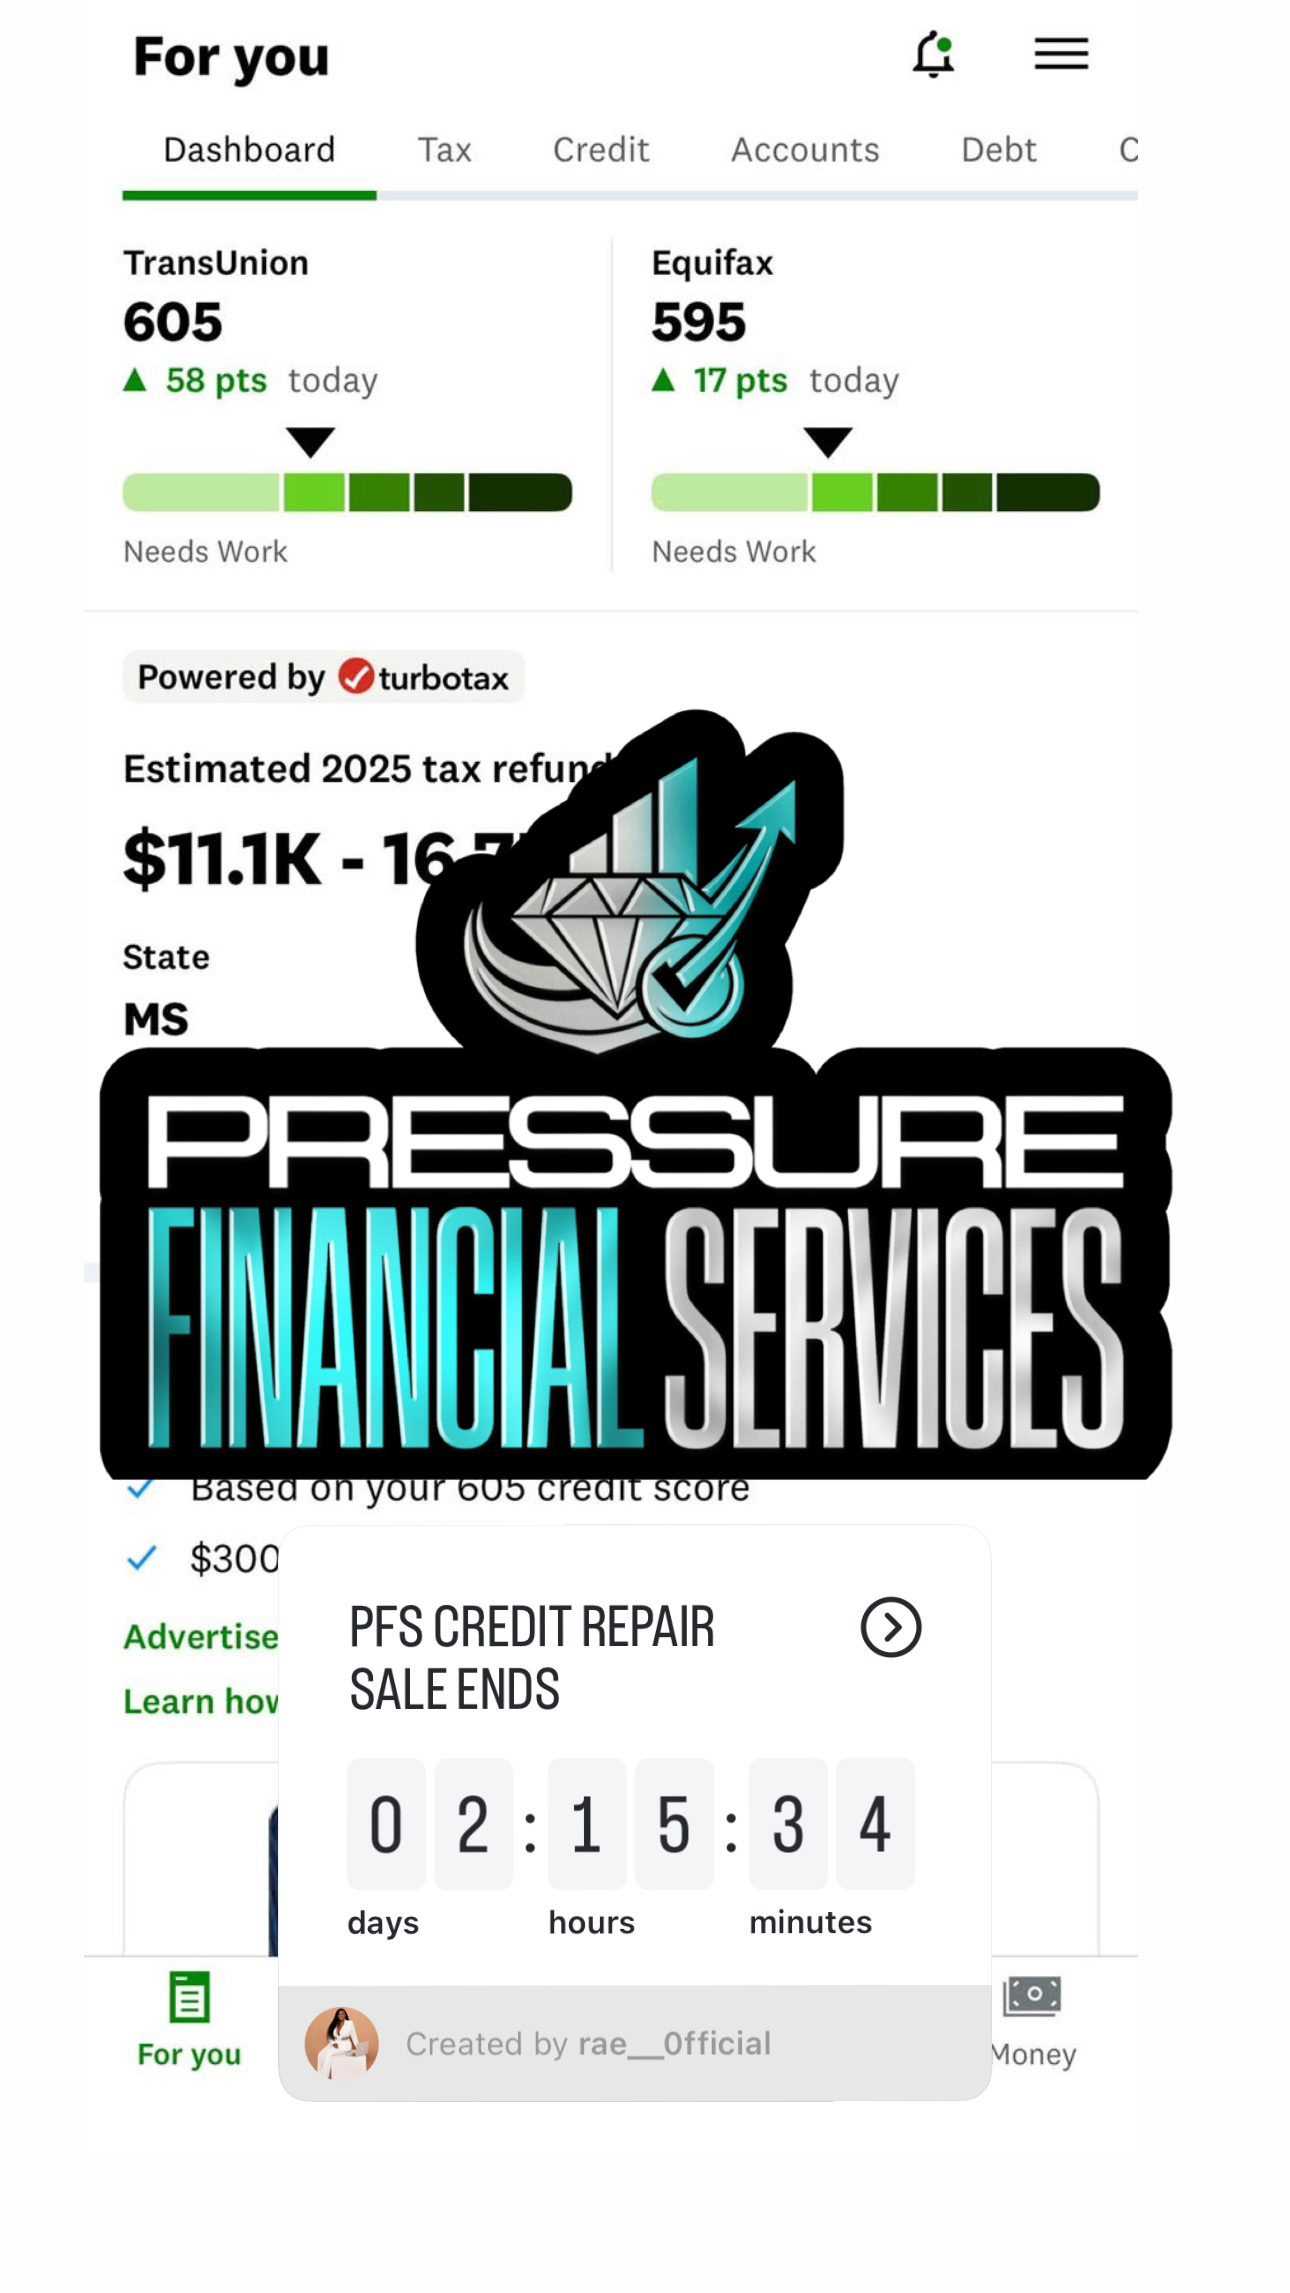
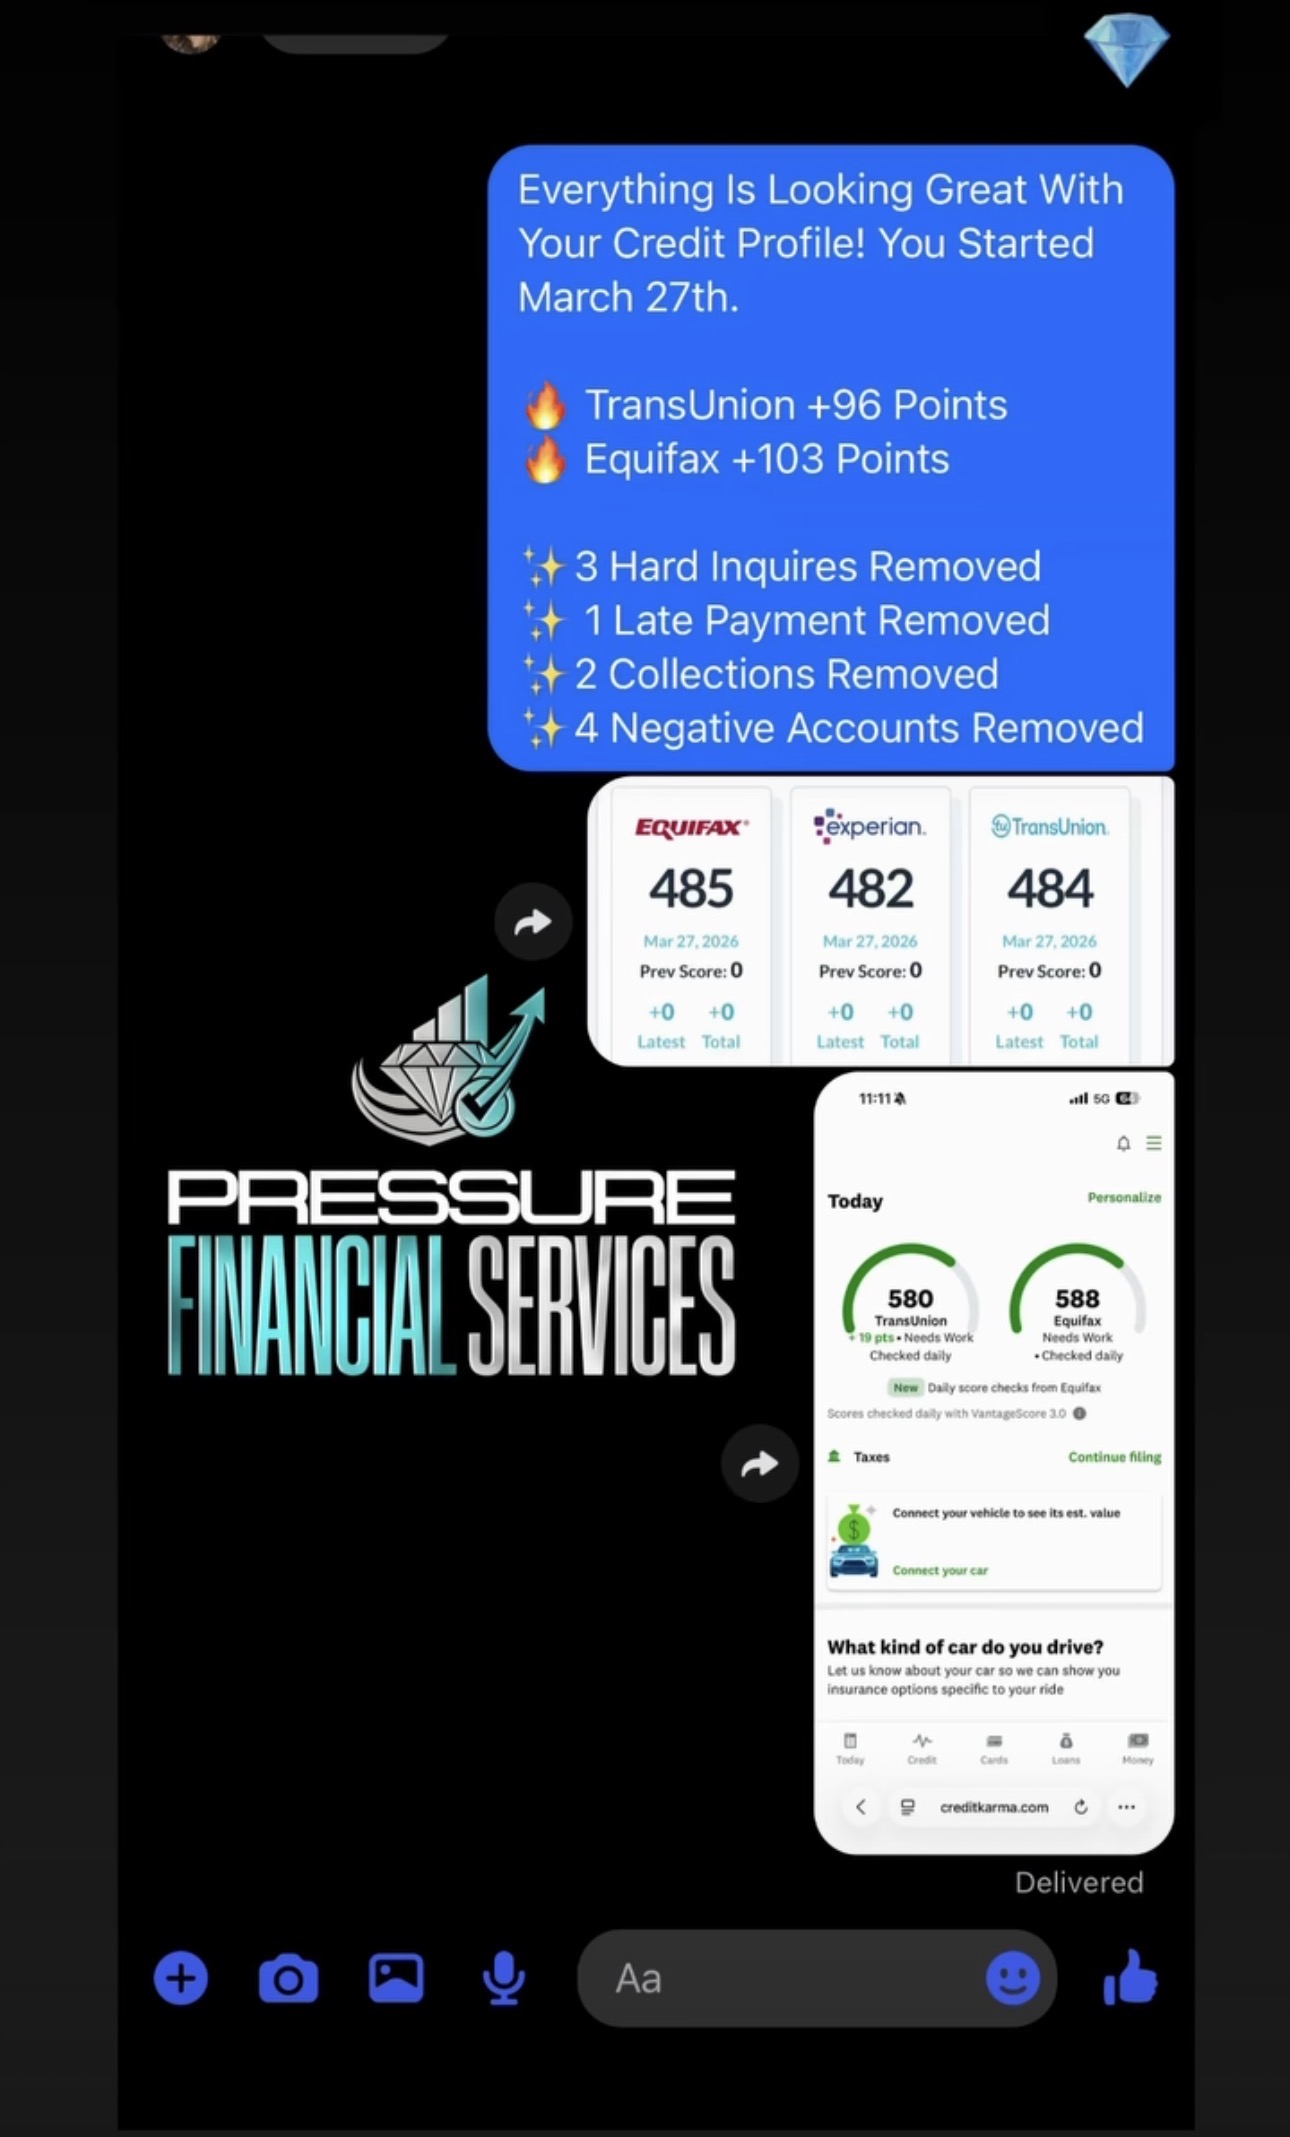
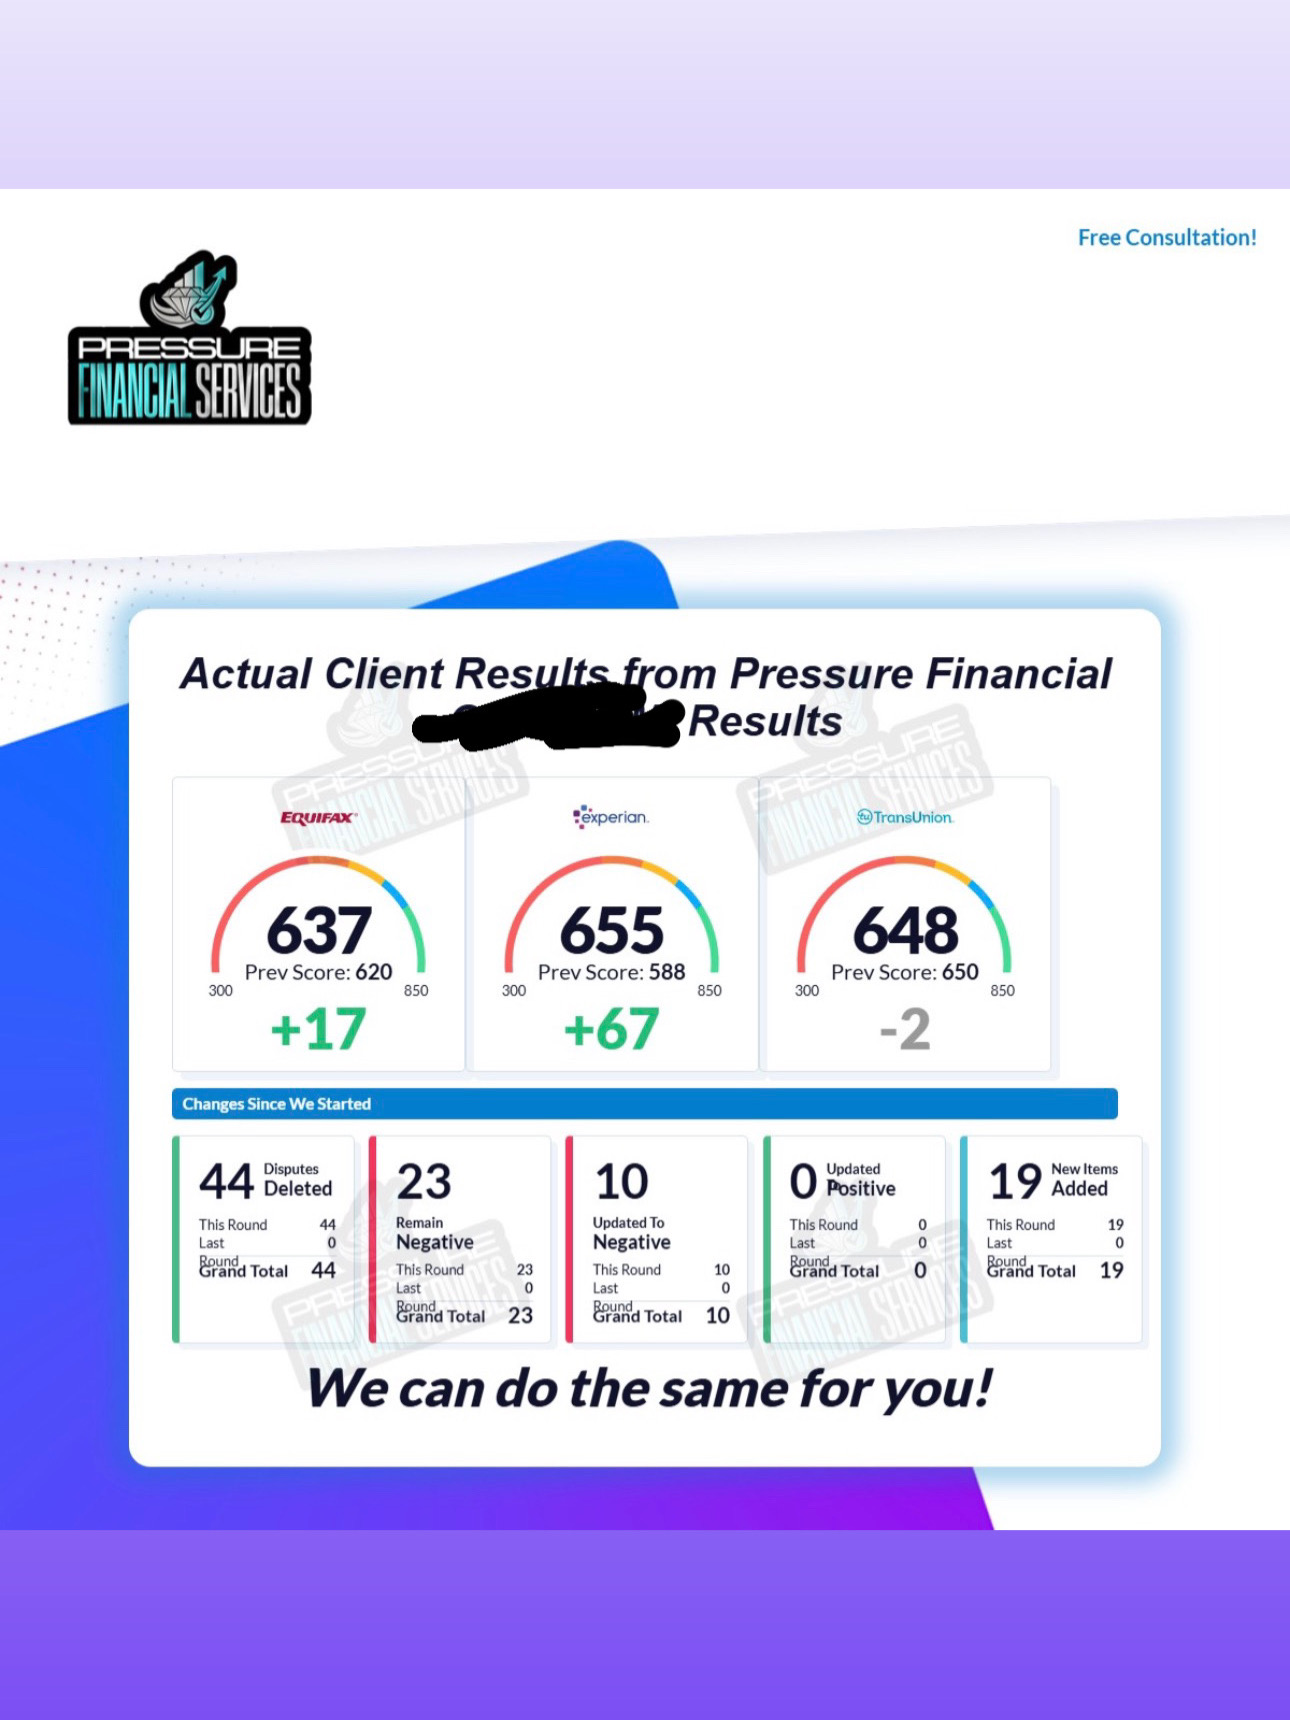
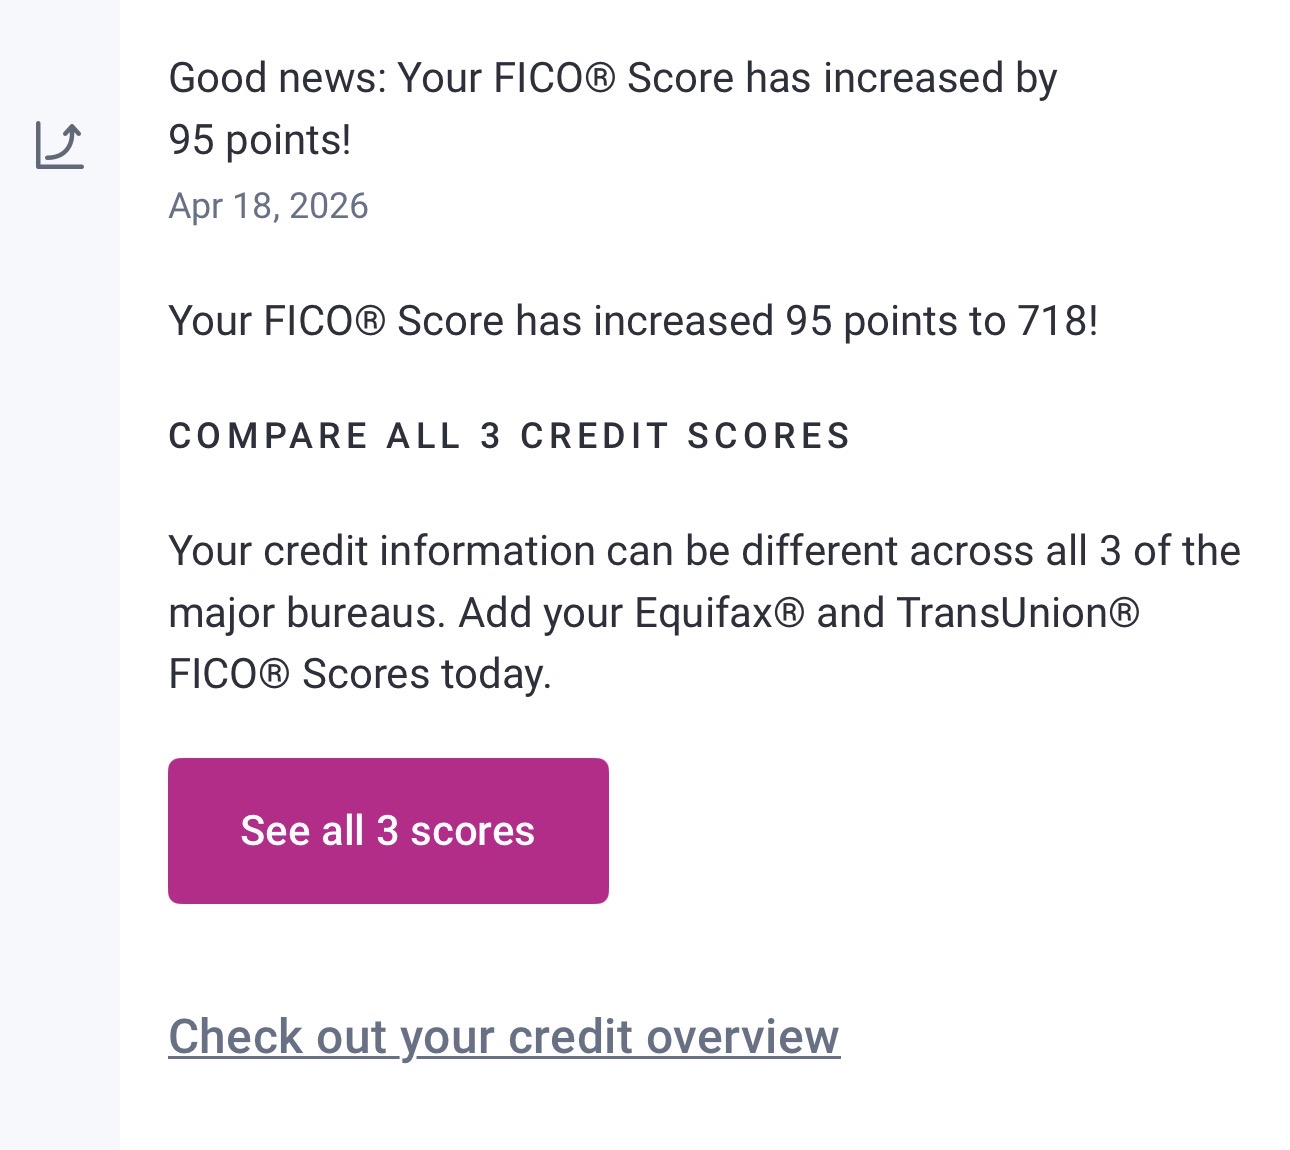
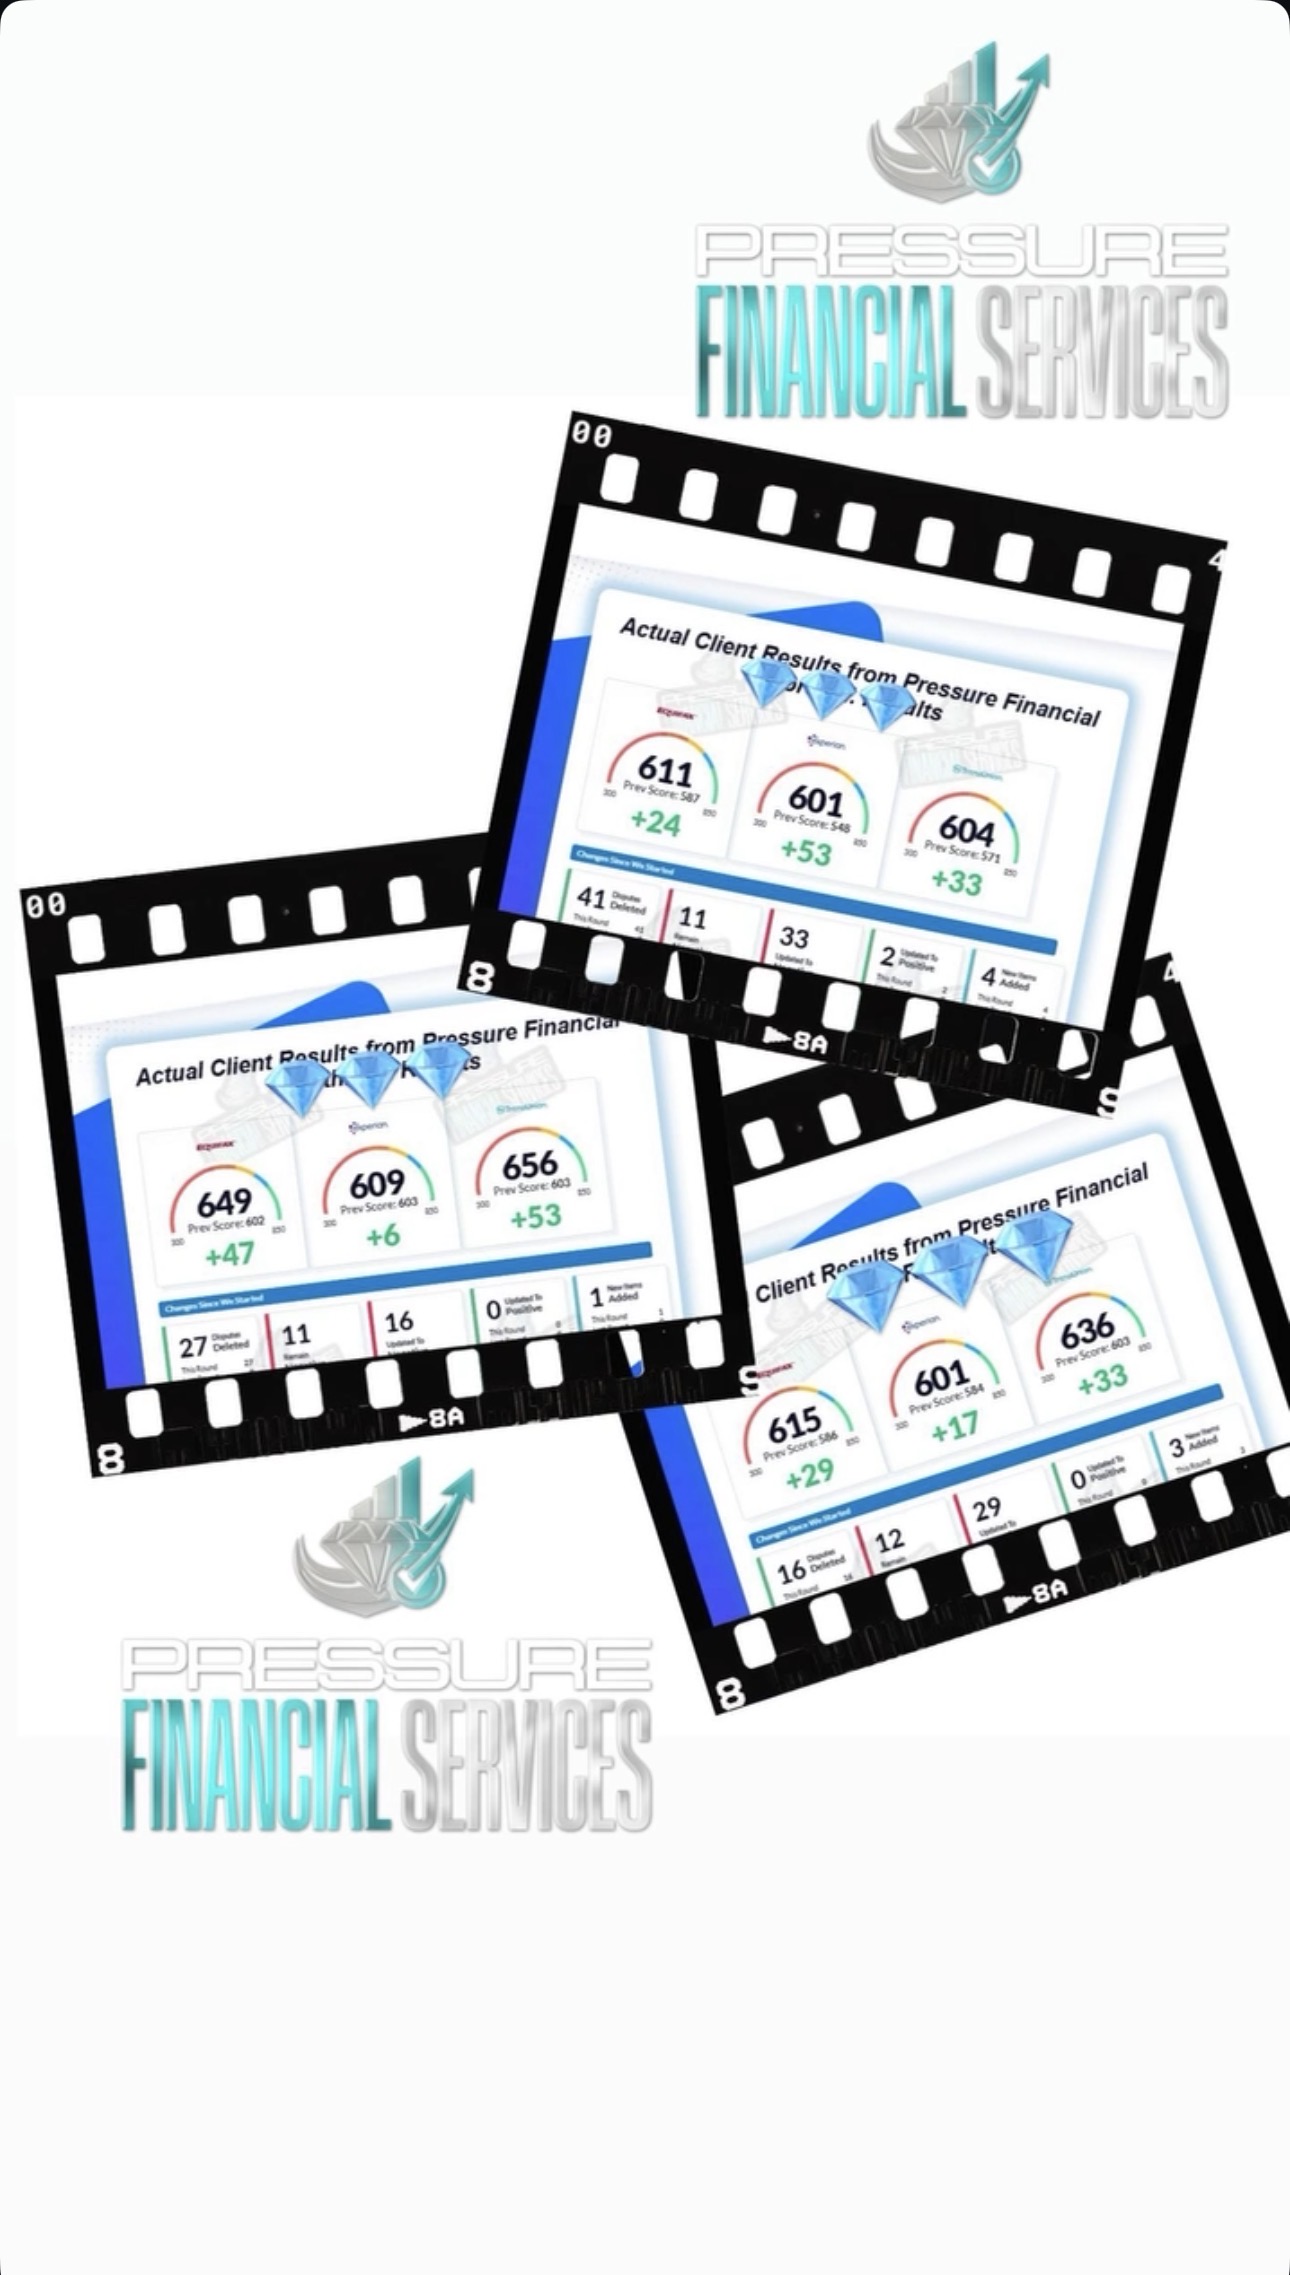
Real Results from Real People
People are getting real wins by following the right structure not guessing anymore.
Frequently Asked Questions
How does credit repair work?
We analyze your credit reports, identify inaccurate or negative items, and strategically dispute them with the credit bureaus and creditors. At the same time, we guide you on how to build positive credit so your score increases the right way.
How long does credit repair take?
Most clients start seeing results within 30–45 days, with stronger progress in 60–90 days. Full results depend on your credit profile, but most clients stay in the program 3–6 months.
Can you remove all negative items?
No company can legally guarantee that all items will be removed. However, we focus on removing inaccurate, outdated, or unverifiable items and improving your overall credit profile for better approval odds.
Will my credit score go up?
In most cases, yes—but results vary. Our goal isn’t just a higher score, it’s a stronger credit profile that gets you approved.
What items can be removed?
We work on:
* Collections
* Charge-offs
* Late payments
* Hard inquiries
* Some repossessions
Do I need to pay off my debt first?
Not always. In many cases, paying off collections incorrectly can actually hurt your score. We guide you on what to pay, when to pay, and how to handle it strategically.
Is credit repair legal?
Yes. You have the legal right to dispute inaccurate information under the Fair Credit Reporting Act (FCRA).
Will this affect my ability to apply for credit?
During the process, we may advise you to limit new applications temporarily to avoid lowering your score.
Real Results from Real People
People are getting real wins by following the right structure not guessing anymore.
Frequently Asked Questions
How does credit repair work?
We analyze your credit reports, identify inaccurate or negative items, and strategically dispute them with the credit bureaus and creditors. At the same time, we guide you on how to build positive credit so your score increases the right way.
How long does credit repair take?
Most clients start seeing results within 30–45 days, with stronger progress in 60–90 days. Full results depend on your credit profile, but most clients stay in the program 3–6 months.
Can you remove all negative items?
No company can legally guarantee that all items will be removed. However, we focus on removing inaccurate, outdated, or unverifiable items and improving your overall credit profile for better approval odds.
Will my credit score go up?
In most cases, yes—but results vary. Our goal isn’t just a higher score, it’s a stronger credit profile that gets you approved.
What items can be removed?
We work on:
* Collections
* Charge-offs
* Late payments
* Hard inquiries
* Some repossessions
Do I need to pay off my debt first?
Not always. In many cases, paying off collections incorrectly can actually hurt your score. We guide you on what to pay, when to pay, and how to handle it strategically.
Is credit repair legal?
Yes. You have the legal right to dispute inaccurate information under the Fair Credit Reporting Act (FCRA).
Will this affect my ability to apply for credit?
During the process, we may advise you to limit new applications temporarily to avoid lowering your score.